Showing posts with label current usd/inr. Show all posts

Thursday, 12 July 2012

Nifty & USD/INR Report- 12th July, 2012

Daily Nifty Analysis

Nifty Analysis By xDirect India
Indian equities extended intraday losses and is near day’s low as traders continued to book profits after a sharp up-move in last session and weak global cues. Brokers said reports of less than average monsoon rains this season might hamper efforts to boost economy and hurt company earnings this quarter impacted the market sentiment. The IMD said that monsoon, the life- line of Indian agriculture, has covered the entire country but rains are still deficient by 23%. Indian markets ended today`s session on a lower note on the back of weak global cues and heavy selling witnessed in auto, FMCG, realty and metal stocks.

The gap down open in the market has definitely enabled the sellers to prompt their activities considering we had yet other depressing FOMC minutes where no sign of QE was provided. This shifted the mindset of traders which now in turn are in selling activities. The immediate resistance comes in at 5290 levels followed by 5325 levels on the rising trend line (former support and now resistance). Expect selling pressure to remain at higher levels unless we have a fundamental trigger which makes the price action to close above 5320 levels, would negate the bearish bias.


View on Indian Rupee

USD/INR Analysis By xDirect India
The Indian Rupee extended losses on Monday falling to its lowest levels in almost a week led by weak cues across the Asian and European stocks markets and post the acute drop in the Euro on Friday which slipped to its two year lows below the 1.2300 level. Broad weakness in the domestic stock markets also put pressure on the local currency which finished with a loss of a percentage yesterday. It seems even though a slight positive reaction in the European currencies did not aid any boost to risk appetite neither towards appreciation to INR value. We therefore require a more of a fundamental trigger that would enable an upside in the same.

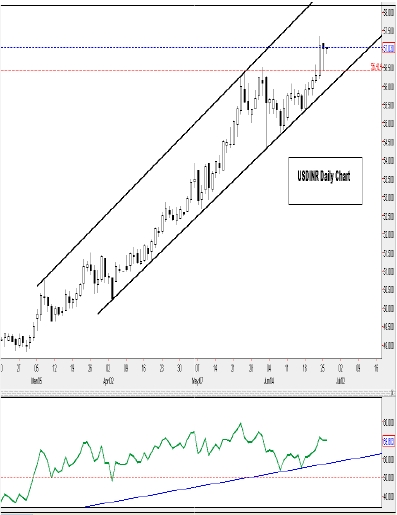
The USDINR pair seems to hold its daily Fibonacci support at 55.74 and if it continues to do so then we are looking at 55.92, 56.08 and then 56.14. However a break of intraday low which is also the support (Fibonacci) then 55.65 followed by 55.50 would be tested. We keep our bias on the upside.


Report By
xDirect India
www.xdirect.in


Monday, 9 July 2012

Nifty & USD/INR Report- 9th July, 2012

Daily Nifty Analysis

xDirect India's Nifty Analysis_09.07.2012
The Indian markets are poised to trade lower today tracking weak Asian session, as major cues were taken from Friday’s soft session in US markets due to lower additions in the employment report for the month of June. This has inflamed economic concerns that has actually paved for equity markets to trade lower and thus has indeed choked on Indian equities forcing them to par their mild gains that has been incurred in the previous week.

 The rate cut by ECB and China has been factored in last week, but what keeps pressure going on the equity markets too trade in the negative would be the deprecating value of the home currency and moreover with oil prices shooting back are providing concerns on the debt factors in the economy. However the monsoon climate could have provided some sort of respite in an otherwise bear market conditions.

 Nifty has its immediate support of 5290 (RISING TREND LINE) from where it’s trading at above 5300 levels; nevertheless we have to see a daily close above from its previous week top 5352, which therefore would only negate the bearish front of the market. Supports at 5292, 5270 followed by 5212. Resistance at 5337, 5352is witnessed. We firmly believe that the mild gains could be only due the factor that expectations were high on the US employment conditions, however neither an improved employment numbers nor an increased bets on QE expectations stoked equities higher that resulted in it to build a top and therefore may slide down towards 5250 levels.


View on Indian Rupee

xDirect India's USD/INR Analysis_09.07.2012
The Indian Rupee fell around 0.8% on Friday taking overall weak cues from the global markets amidst dollar demand from importers, overshadowing the sustained capital inflows into the Indian capital markets over past couple of trading sessions.
Amongst the global markets, the EUR/USD fell sharply in evening trade while the US Dollar index jumped firmly above the 83 mark after lower than expected US  data on  Jobs.  The US  Labor Department said on Friday Non-farm payrolls expanded by just 80,000 in June against expectation of 100,000 additions. This triggered a rally in US dollar and government treasury due to ultra safe heaven.
The Indian Rupee is expected to start the week on a negative as sharp drop in the US markets on Friday is and rise in the Dollar index is exerting pressure on Asian Stock and key currency markets. The EUR/USD is trading at two year lows which are further seen impacting the INR on the downside.

Report By
xDirect India
www.xdirect.in


Tuesday, 26 June 2012

Nifty & USD/INR Report- 26th June, 2012

Daily Nifty Analysis

xDirect India's Nifty Analysis_26.06.2012
Benchmark indices ended weak erasing early gains, as investors were not impressed by the RBI’s measures to stem the rupee’s fall and the government did not announce any reforms as pledged last week. RBI enhanced the FII limit in G-Secs to $20 billion from $15 billion. It also allowed Indian companies in infrastructure to borrow through the ECB route up to $10 bn. The low amount of liquidity would obviously take away volatility and volumes which eventually turned out to be a negative session for the Nifty. Even the global markets were quite sticky with risk aversion combined with overselling kept the price movements range bound with the US Dollar just bouncing on every dips.

With the sudden drop in the market being witnessed yesterday, the government has announced today that it would take necessary steps to stem the Rupee depreciation; nevertheless these comments came in futile as global uncertainty has indeed gripped on the bull traders to resume on their trading with INR still hovering at its all-time low levels. For today we have a light on the counter from Euro Zone and UK, but US Consumer Confidence being the most important. However the Indian markets would trade sideways with supports coming in at interim levels of 5095 levels (Rising trend line). Followed by 5050 (50% retracement) and then 5023 (Falling trend line). Resistance is seen towards 5140, 5178 levels; however considering bearish trend has been commenced we believe Nifty has little chance of building momentum over 5180 levels for the week.

View on Indian Rupee

xDirect India's USD/INR Analysis_26.06.2012
The Indian Rupee gained sharply in yesterday’s trade bolstered by the expectations of big-bang policy measures from the Government of India and the RBI. The Rupee opened sharply higher and continued rising to make a high near the 56.3750 level. Though it weakened from day’s high and ended at 57.01 to the US Dollar after the measures  introduced by the RBI disappointed markets.

The main step announced was to increase in the cap on foreign investment in Indian government debt  to  $20  billion  from  $15  billion.  The government also reduced the minimum period investors need to hold some bonds to three years from five years, making them more attractive to foreign funds.

The Indian Rupee is expected to trade in a tight spot where in, where on the upside the resistance is seen towards 57.42 (Fibonacci extension) followed by 57.65 levels. Supports come in at 56.40 (yesterday session low). There might be some sort of positives seen in the market considering the constant selling but we believe the bear trend would resume considering the ill-liquid FOMC state,, followed by the multiple downgrades. For today however we would want the US Consumer Confidence to give some amount of boost as yesterday’s housing sales marked good numbers, its best in 3 years.


For today the market is expected to be range bound however, where European session may mark some amount of swings in the global market which may give certain movement in the currency pair.

Report By
xDirect India
www.xdirect.in


Thursday, 21 June 2012

Nifty & USD/INR Report- 21st June, 2012

Daily Nifty Analysis


Nifty Analysis_21.06.2012_xDirect India
The choppy but somewhat positive movements in yesterday’s global market have indeed given Indian equity markets the required boost. Nevertheless the swings on both ends were provided by the fundamental trigger given by Bank of England that apparently chose to boost the stimulus regime in the economy which indeed is required for to boost the banking sector in the region. However the bets on QE kept on rising till the end of Indian markets that managed to close in the positive. The positive terrain was led by the sectors in Metals, Capital Goods, healthcare and Automotives.

Today however as the QE bets faded some amount of pressure could be eased for the markets to look forward to the negative side of the global economic scenario. Where as they have factored on the QE it is now to look forward to the fundamental triggers from the Euro Zone end, while today market has opened slightly on the flat note further swings would be provided by the reaction in the European markets.


The immediate support on Nifty comes in at 5080 levels (50% retracement) and only a breach of this would threaten in another bout of selling in the counter, where the support levels would be followed in by 5043 (falling trend line). Resistance comes in at 5140 levels and if the levels close in anywhere around or over it then we would change our bias to positive on the same, where the price action played in within the confines of this levels then it would be range -bound play.


View on Indian Rupee

USD/INR Analysis_21.06.2012_xDirect Ind
The Indian Rupee closed in the negative as despite the Indian equities managing to close in the positive did not provide the necessary boost to Indian Rupee that closed lower against the US Dollar.
Amongst other major news in the domestic markets, rating agency Fitch revised the outlook of a no. of major Indian banks including SBI, PNB, Bank of Baroda, Canara Bank, IDBI Bank, ICICI Bank, Axis Bank, EXIM Bank of India among others.

In the global space, the major US Federal Reserve meeting ended yesterday wherein the Central bank kept its interest rates on hold and extend its so called Bond buying program named Operation Twist towards the end of this year. The Fed said it will prolong the program and expects to sell $267 Billion of shorter-term securities and buying the same amount of longer- term debt in a bid to cut borrowing costs and spur thee economy. Both the moves were widely anticipated by thee markets and couldn’t spur any kind of positivism.


Today technically the Spot USD/INR is at a standpoint of either breaking the resistance of 56.42 therefore marking a new highh towards 57.00 levels, or holding those levels that would be only be possible for a string of positive data’s to tests its intraday low of 56.10 and even though this level would be considered for initiating a buy we would recommend to ponder on the European & US equity markets that would break the levels of 56.10 to test lower levels of 55.80 to 55.70.


Report By

xDirect India

www.xdirect.in


Tuesday, 19 June 2012

Nifty & USD/INR Report- 19th June. 2012

Daily Nifty Analysis


Nifty Analysis_19.06.2012_xDirect India
The ongoing worries of Spain that pushed its yield rates to over 7.25% yesterday is overshadowing the Greek elections that came out to attempt a positive vibe in the global market. However, it was soon faded as borrowings become more expensive in the Euro Zone debt ridden nations. The one domestic fundamental that could have provided the much needed support would have been the RBI monetary policy decision; nevertheless all its rates (including CRR) were kept unchanged as RBI still thinks that inflation would be the more sought out problem rather than growth for the economy. European markets too ended mixed as worries about Spain and Italy dominated investor sentiment. Italy and Spain markets closed with 3% losses, while Germany, France and UK markets ended mixed. With no major data reported yesterday, US markets closed in mixed with Dow Jones slipping 0.20% while S&P 500 and NASDAQ eking out gains of 0.14% and 0.78% respectively.

Nifty closed in the negative by 75 points at 5064 just below its support of 5065;; moreover those alone weren’t the only problems that were to be faced as FITCH lowered India’s sovereign debt rating to negative from stable.


 For today the markets could come under pressure; however it could turn out that trading would be mixed as we turn into FOMC rate decision on Wednesday and the possible reactions to it. Therefore the support levels for intraday lies in 5060 levels (Falling trend line) followed by 5012 levels (horizontal Line support). Only a breach of 5044 levels could trigger another bearish trend for the Nifty to test 4954 levels (61.80% retracement). Resistance at 5082-5090 levels (50% retracement) followed by 5120 levels.

View on Indian Rupee


USD/INR Analysis_19.06.2012_xDirect India
The Indian Rupee slipped to its lowest levels in almost a week on Monday after the domestic central bank kept the benchmark interest rates unchanged, while Fitch downgrade of country’s outlook and late session cues from the European markets also hurting sentiment. The partially convertible Rupee fell to as low as 56.04 to the USD in the latter half taking domestic and global cues while closed at 55.9050 against the US Dollar as compared to Friday’s finish at 55.39.

Weakness in the local shares to contributed to the weakness in the INR. Indian shares dropped more than 1.4% marking their biggest percentage fall since June 1, led by a sell-off in Banking and financial sector after the central bank unexpectedly kept interest rates on hold. The RBI in its monetary policy review cited its continued concerns about inflationary pressures and weakening domestic fundamentals for no change in rates.


The home currency is expected to open lower on Tuesday tracking weakness in the Asian markets and after the EURUSD fell sharply against the day’s high at 1.2750 levels yesterday. Today morning, the common currency is trading with marginal gains which might provide some support to the local unit, though overall trend seems to be weak.

Report By

xDirect India

www.xdirect.in

Friday, 15 June 2012

Nifty & USD/INR Report – 15th June, 2012

Daily Nifty Analysis

Nifty Analysis_15.06.2012_xDirect India
Indian markets dropped over 1% on Thursday on concern the higher than expected inflation will reduce possibility of aggressive monetary easing by the RBI on June 18. The WPI inflation for the month of May rose to 7.55% as against the previous month`s figure of 7.23% and previous year`s corresponding month`s figure of 9.56%. Moreover the March inflation was revised upwards from 6.89% provisional to 7.69%. Weak European markets further intensified the selling pressure. At the close, the benchmark 30-share index, BSE Sensex declined 202.63 points or 1.20% at 16,677.88 with 26 components posting drop. Meanwhile, the broad based NSE Nifty went down by 66.70 points or 1.30% at 5,054.75 with 44 components posting drop. Market is expected to open on positive note and likely to remain range bound ahead of Greece election on Sunday. More Americans applied for jobless benefits and consumer prices dropped by the most in three years, giving the Federa Reserve room to spur an economy that’s generating little growth or inflation. Claims for unemployment insurance payments unexpectedly climbed by 6,000 to 386,000 in the week ended June 9, Laborr Department figures showed in Washington.

Outlook for today Nifty has an immediate resistance at 5,090-5,100 levels; on a decisive close above expect rise to 5,140 & 5,180 levels. However with early Asian markets in the positive we expect the markets too would perform in a likewise manner moreover with INR appreciating would give out further confidence to the Indian equity overall. We therefore would like to initiate a buy at 5082 (former resistance and now support) for the target of 5150 levels. Stop Loss to be placed at 5045 (previous session low).

View on Indian Rupee

USD/INR Analysis_ 15.06.2012_xDirect India
The Indian rupee gains v/s the US dollar on Friday on the back of firm move in the domestic share market. On Friday, the rupee suffered from falls in global risk assets on the back of the lack of clarity on potential U.S. monetary stimulus, worries China will post weak data on Saturday, and concerns about Spanish banking woes.
Today, the sentiment is positive in the global market with stock markets, the euro and oil rallied after less bad Chinese data then expected along with a Spain’s bank bailout. The market welcomed the weekend news that Spain secured a EUR100 billion ($125 billion) loan to bolster its banking system, which makes the country the fourth and largest Euro Zone economy to be rescued by its euro-zone partners.
On Saturday, China released economic data which showed a weakening economy, but was not as bad as some expected. The PBoC made a surprise cut to interest rates ahead of the data, which was taken as a signal by the market that May’s figures were going to be very bad. As per data, China’s trade surplus was $18.7bn in May, a touch bigger than its $18.4bn surplus in April. Industrial production nudged up to a 9.6 per cent rise from 9.3 per cent in April. Inflation receded to 3.0 per cent year-on-year in May, the lowest in two years and down from 3.4 per cent in April. Today, the Japan’s Nikkei climbed 2% and Hong Kong’s Hang Seng Index gained 2.1% and Korea’s Kospi was 1.7% higher. Singapore’s Strait Times Index rose 1.5% and the China Shanghai Composite was up 0.3%.

Immediate support is at 55.30 and 55.10 levels. Intraday resistance is at 55.43 and then at 55.55 levels. Any pullback towards the resistance is ideal for selling.


 Report By
xDirect India
www.xdirect.in


Thursday, 14 June 2012

Nifty & USD/INR Report – 14th June, 2012

Daily Nifty Analysis

Nifty Analysis_14.06.2012_xDirect India
Indian equity indices managed to pull back from session lows, they closed just marginally higher, as uncertainty over the RBI policy action on June 18th kept market players wondering on the result that would affect the outcome to Indian capital markets. The undercurrent was also cautious before the release of the latest WPI inflation report on Thursday. Major Asian markets posted decent gains while the European markets were trading nearly flat after a higher start. Worries over the euro zone credit crisis persisted ahead of Italian bond auction later this week and Greek Elections on June 17.
There was a volatile trading session witnessed in Nifty yesterday, where it ended the session with a mere 18 points gain; however did scale up over the resistance line of 5100 levels, poising to touch 5150 levels for the day; however we do have the WPI data that is to bee reported which may cause some amount of rift as traders gear up for the RBI rate policy decision next week.
Support lies in at interim levels of around 5100, followed by 5080-5075 levels and then 5025levels. If there are dips in the market then it should be as an opportunity to buy in the market; however on the global front we do have Greece elections to come up this Sunday. Resistance at 5150 followed by 5210 (38.20% retracement is witnessed)

View on Indian Rupee

USD/INR Analysis_14.06.2012_xDirect India
The currency market remains indecisive yesterday  before  the  crucial  Greece election on 17th June and Italian bond sale which is due today. In the global market, the EURUSD remained higher despite Moody’s cuts Spain rating to Baa3 from A3. Further cuts may come, according to Moody’s, warning that the country may eventually be cut to junk. Spain’s is not in a position for A or BAA ratings, the agency said. We presume due to dismal data on the retail growth in US that reported an unchanged improvement from its previous levels of -0.20% states that US consumers hasn’t revived their consumption habits, in which the nation thrives on.

Indian Rupee Intraday Outlook:
However after the initial rally till 1.26 on EUR/USD there was a slight pullback however we presume that some sort of risk-off  trigger  if  provided  then  a downside on EUR/USD could result in US Dollar buying eventually pushing USD/INR once again to over 56.00 levels.
We expect USDINR to trade sideways with Italian bonds which would be in focus for today. A good bid on the auctions would definitely play a good role in risk –on environment   giving   boost   to   INR appreciation.

 Report By
xDirect India
www.xdirect.in


Blog Archive